
In a nutshell: Crypto tax loss harvesting means selling crypto that is worth less than you paid, so the realized loss can offset your capital gains and, in the US, up to $3,000 a year of ordinary income ($1,500 if married filing separately), with any extra carried forward. As of October 5, 2026, the US wash-sale rule still covers only stock and securities, not ordinary crypto like bitcoin. But a bill now in Congress would change that and could reach back to sales after September 14, 2026. Educational only; not tax or financial advice.
Last updated: October 5, 2026. Tax rules and pending legislation change. Check current IRS guidance or a tax professional before you act.
This guide explains how crypto tax loss harvesting works for US taxpayers: the loss limits, where the wash-sale rule stands in 2026, reporting, a worked example, and how Canada differs. For the bigger picture, see our US crypto taxes guide.
Table of contents

What Is Crypto Tax Loss Harvesting?
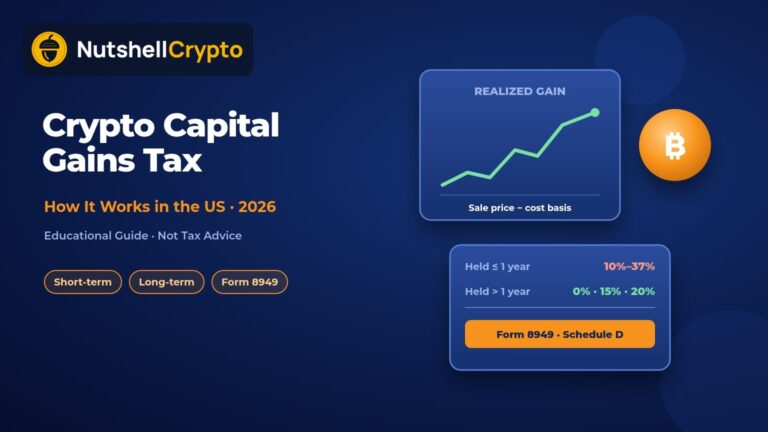
The IRS treats digital assets as property, not currency. When you sell, swap, or spend crypto, you have a capital gain or loss: what you got minus your cost basis (usually what you paid).
A loss only counts once it is realized. Coins that are down on paper give you nothing to deduct. Harvesting means deliberately realizing the loss, usually by selling, so it reduces tax on your other gains.
Two points to remember:
- Crypto-to-crypto swaps count. The IRS treats exchanging one digital asset for another as a disposal, so it can realize a loss too.
- It mostly defers tax. If you buy back in, your new basis is lower, so a later sale may show a bigger gain.
How US Capital Losses Work
According to the IRS (Topic No. 409):
Short-term vs long-term
Held one year or less means short-term (taxed at ordinary rates). Held more than one year means long-term (usually lower rates). Losses offset same-type gains first, then the other type.
The $3,000 limit and carryforward
If your capital losses are larger than your capital gains, you can deduct the smaller of $3,000 ($1,500 if married filing separately) or your net loss against other income, such as wages. Any loss above that limit carries forward to later years, where it can offset future gains plus another $3,000 a year of income.
The deadline is the sale date
A loss belongs to the tax year in which you sell or dispose of the asset. To use a loss on your 2026 return, the sale has to happen in 2026, by December 31.
Does the Wash-Sale Rule Apply to Crypto in 2026?
Current law (as of October 5, 2026)
The wash-sale rule in Internal Revenue Code §1091 blocks a loss when you sell stock or securities at a loss and buy substantially identical stock or securities within 30 days before or after the sale. The IRS Schedule D instructions say the rule “generally appl[ies] to transactions involving digital assets that are also stock or securities for tax purposes (tokenized securities).” Ordinary cryptocurrencies like bitcoin and ether are treated as property, and we did not find any IRS guidance applying §1091 to them. So under current law, a loss on directly held crypto is generally not blocked by the wash-sale rule, even if you buy back within 30 days.
A pending bill could change that, with an earlier start date
On September 14, 2026, the Digital Asset Tax Certainty Act (H.R. 10357) was introduced in the House. Section 301 would extend §1091 from “stock or securities” to “specified assets,” including traded digital assets other than qualified US dollar stablecoins. On September 16, 2026, the House Ways and Means Committee approved it 38–5. According to a Joint Committee on Taxation description of the committee’s amended version, it would apply the wash-sale change to dispositions after September 14, 2026.
The bill is not law. Congress.gov lists the committee vote as its latest action, so it has not passed the full House or the Senate. But if it is enacted as written, a loss you harvest now and buy back within 30 days could be disallowed after the fact.
Crypto ETFs are different
Spot bitcoin and ether ETF shares trade through a brokerage like any exchange-traded security, and many brokers and tax professionals apply the wash-sale rule to them. If you harvest an ETF loss, assume the 30-day rule applies.
Worked Example (Hypothetical Numbers)
All numbers below are made up for illustration. They aren’t price predictions or advice.
Sam is a single US filer. In March 2026, Sam sold some ether held for eight months and realized a $5,000 short-term gain. Sam also holds a different coin bought in May 2026 for $12,000 that is now worth $4,000, an unrealized loss of $8,000.
| Step | Amount |
|---|---|
| Short-term gain already realized | +$5,000 |
| Sell the losing coin in November 2026 (short-term loss) | −$8,000 |
| Net capital loss for 2026 | −$3,000 |
| Deducted against ordinary income in 2026 | $3,000 (the full limit) |
| Carried forward to 2027 | $0 |
The harvested loss wipes out the $5,000 gain and also cuts $3,000 from other income. Had the loss been $12,000, $4,000 would carry forward to 2027.
If Sam buys the coin back at $4,000, the new basis is $4,000 and the holding period restarts, so a later rise to $12,000 would be an $8,000 gain. Under the pending bill, a buyback within 30 days could also put this loss at risk.
How to Report It: Form 8949, Schedule D, and 1099-DA
- Form 8949 and Schedule D. The IRS says to report sales and exchanges of digital assets held as capital assets on Form 8949, then carry the totals to Schedule D (Form 1040). You also answer “Yes” to the digital asset question on Form 1040 if you sold or exchanged crypto during the year.
- Form 1099-DA for 2025. Under final IRS regulations, brokers such as custodial exchanges must report gross proceeds on the new Form 1099-DA for transactions on or after January 1, 2025. For 2025 transactions, which were reported in 2026, the IRS said it would not impose penalties on brokers that made a good-faith effort to file correctly and on time.
- Form 1099-DA for 2026 and later. Brokers must also report cost basis for “covered securities.” Under the IRS instructions, that generally means digital assets acquired after 2025 in a custodial account with that broker and held there until sale. Coins you bought earlier, or moved in from another wallet, may show as “noncovered” with no basis reported. You are still responsible for the correct basis.
- Pick your units on purpose. Which units you sell decides the size of your loss. IRS digital-asset FAQs say you can specifically identify units by the time of the sale, or set a standing order with your broker. Otherwise a wallet-by-wallet first-in, first-out default applies. To harvest the biggest loss, check your exchange’s cost-basis settings before you sell.
Mistakes and Risks to Watch
- Selling only for the tax break. Fees, spreads, and a poor investment decision can outweigh the saving.
- Missing records. Keep dates, amounts, and dollar values. Wallet-to-wallet transfers are where basis usually goes missing.
- Trusting the 1099-DA alone. It covers only that broker. Self-custody and DeFi activity still must be reported.
- No sale, no loss. A coin that has dropped but still trades generally can’t be written off while you hold it (see IRS CCA 202302011).
How Canada Differs: The Superficial Loss Rule
Canadian readers face a different system. The Canada Revenue Agency’s capital losses page describes a superficial loss rule. A loss is denied if you or an affiliated person, such as your spouse or common-law partner, buy the same or identical property within 30 calendar days before or after the sale and still own it 30 days after. The denied loss is usually added to the adjusted cost base of the replacement property instead.
Canada also has no $3,000-style deduction against employment income. The CRA’s crypto guidance says allowable capital losses (half of capital losses) can be deducted only against taxable capital gains. Net capital losses can be carried back three years or forward indefinitely. Some crypto activity may count as business income instead of capital. For the full picture, see our guide to cryptocurrency tax in Canada.
Frequently Asked Questions
What is crypto tax loss harvesting?
It means selling or swapping crypto worth less than your cost basis so the realized loss can offset capital gains and, in the US, up to $3,000 a year of ordinary income, with any extra carried forward.
Can I sell crypto at a loss and buy it back right away?
Under current US law (as of October 5, 2026), the wash-sale rule covers stock and securities, not ordinary crypto held directly. But H.R. 10357, approved by the House Ways and Means Committee, would extend the rule to traded digital assets for sales after September 14, 2026, if it is enacted as written. It is not law yet, but quick buybacks now carry that risk.
How much crypto loss can I deduct per year?
Losses offset capital gains without a cap. Beyond that, up to $3,000 ($1,500 married filing separately) a year can offset other income, and the rest carries forward.
Do I have to report crypto losses if I didn’t receive a 1099-DA?
Yes. The IRS says you must report digital asset transactions whether or not they result in a gain or loss, and whether or not a broker sent you a form. Use Form 8949 and Schedule D.
When is the deadline for crypto tax loss harvesting?
The sale must happen during the tax year you want the loss in, which for most people means by December 31.
New to crypto? Our how to buy bitcoin guide covers the basics, including keeping records from day one.
Sources
- IRS: Digital assets (property treatment, Form 8949, Form 1099-DA timeline)
- IRS Topic No. 409: Capital gains and losses ($3,000 limit, carryover)
- IRS: Instructions for Schedule D (wash sales and tokenized securities)
- IRS: Instructions for Form 1099-DA (covered securities)
- IRS: FAQs on digital asset transactions (identifying units)
- Congress.gov: H.R. 10357, Digital Asset Tax Certainty Act
- Canada.ca: Capital losses and the superficial loss rule
- CRA: Reporting income from crypto-asset transactions
- Fidelity: What is tax-loss harvesting?
- Coinbase Help: IRS Form 1099-DA
Educational content only. This is not tax, legal, or financial advice. Tax outcomes depend on your situation, and pending legislation may change the rules. Consult a qualified tax professional before acting.