
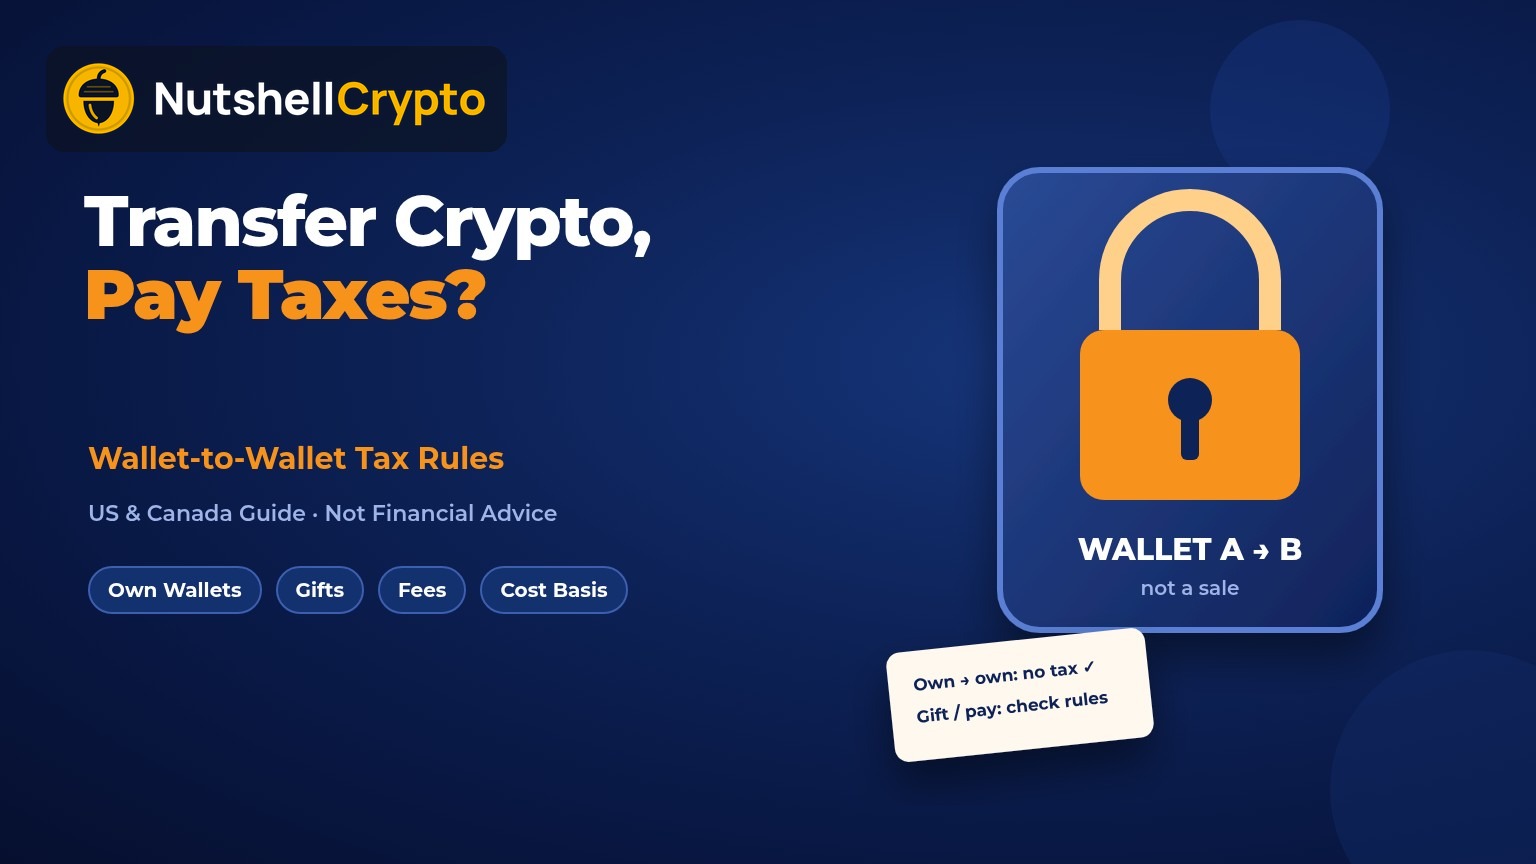
In a nutshell: If you transfer crypto between wallets or exchange accounts that you own, you usually do not pay tax, because in both the US and Canada that move is not a sale. Tax can apply when the transfer is really a disposal: sending crypto to pay for something, gifting it, or (in some cases) paying network fees in crypto. Educational only; not financial or tax advice.
Last updated: October 9, 2026.
Moving bitcoin from Coinbase to a hardware wallet, or USDC from one app to another, is one of the most common things crypto owners do. It is also one of the most common sources of tax confusion, because many exchanges show a “send” as if the coins left your hands. This guide explains when a crypto transfer is tax-free, when it is not, and how to keep records so a simple move does not turn into a reporting headache in the US or Canada.
Table of contents
If I Transfer Crypto, Do I Pay Taxes? The Short Answer
No, not when you are only moving your own coins. Tax in both countries is triggered by a disposal: selling crypto for cash, trading one coin for another, spending it, or giving it away. Moving coins from one wallet you control to another wallet you control does not change who owns them, so there is no gain or loss to report at that moment.
The IRS says this directly in its virtual currency FAQs: if you transfer virtual currency from a wallet, address or account belonging to you to another wallet, address or account that also belongs to you, the transfer does not result in a taxable event. The CRA’s guide for cryptocurrency users uses the same idea of a “disposition”, and moving property you still own between your own accounts is not one.
That does not mean transfers can be ignored. They affect your records, your cost basis and sometimes the forms an exchange sends you. Those details are where most mistakes happen.
Transfers Between Your Own Wallets
These moves are normally not taxable:
- Exchange to your own hardware or software wallet, such as moving coins into self-custody.
- Your wallet back to an exchange account in your name.
- One exchange account to another exchange account you own.
- Between two wallets you control, for example a hot wallet and a cold wallet.
- Bridging or wrapping in some cases, though this is a grey area (see the FAQ).
The key test is ownership. If the same person (or the same legal entity) owns the coins before and after the move, there was no sale. Your original purchase date and cost basis travel with the coins. If you bought 0.5 BTC for $30,000 two years ago and moved it to a Ledger, it is still 0.5 BTC with a $30,000 basis and a two-year holding period.
When a Crypto Transfer Can Be Taxable
A “transfer” in your wallet history can still be a taxable event when ownership changes or when you get something in return:
- Paying for goods or services. Sending crypto to a merchant or a freelancer is treated like selling it at fair market value and spending the cash. You report a gain or loss against your cost basis.
- Swapping into another coin. If a “send” actually goes through a swap (ETH to USDC, for example), that is a crypto-to-crypto trade and a disposal in both countries.
- Gifting crypto. The rules differ sharply between the US and Canada (explained below).
- Sending to a different person or entity. Moving personal coins into your company’s wallet, or the reverse, is a transfer between two different taxpayers. It can be a sale, a contribution or a distribution depending on the structure. Our guide to a crypto wallet for business covers why company and personal funds should stay separate.
- Receiving crypto. Getting paid in crypto, or receiving staking rewards, is generally income when you receive it, not a transfer.
What About Network Fees Paid in Crypto?
Fees are the part most people miss. When you send ETH and pay a gas fee in ETH, a small amount of ETH leaves your control and goes to the network. Many tax professionals treat that fee as a tiny disposal of the crypto used to pay it, which can create a very small gain or loss. The IRS has not issued detailed guidance that settles how transfer fees between your own wallets should be handled, so practice varies and crypto tax software handles it in different ways.
For most people the amounts are small, but on a busy chain or with many transfers they add up. The safest habit is to record the fee, the coin used and its value at the time. If you use an exchange, our guide to crypto exchange fees explains withdrawal fees and how they show up on statements.
US Rules: IRS, Cost Basis and Form 1099-DA
The IRS treats digital assets as property. Every federal return asks the digital asset question, and you must answer it accurately even if your only activity was moving coins. Holding crypto or transferring it between your own wallets on its own lets you answer “No”, according to the IRS instructions, while selling, trading or spending it means “Yes”.
Three US details matter for transfers:
- Wallet-by-wallet cost basis. Starting January 1, 2025, the IRS requires cost basis to be tracked per wallet or account rather than across all your holdings (see Revenue Procedure 2024-28). When you move coins, their original basis must move with them in your records.
- Form 1099-DA. Brokers started reporting gross proceeds on the new Form 1099-DA for sales made in 2025, with cost basis reporting for many assets starting with 2026 sales. If you move coins into an exchange and sell there, the exchange may not know what you paid, and the form can show a missing basis. You fix that with your own records.
- Gifts. Giving crypto is not a taxable sale for the giver. Gifts above the annual exclusion ($19,000 per recipient for 2025 and 2026) require a gift tax return (Form 709), although tax is rarely owed because of the lifetime exemption. The recipient generally takes over your cost basis.
For how gains are taxed when you finally sell, see our guides to crypto taxes in the US and crypto capital gains tax.
Canada Rules: CRA and Adjusted Cost Base
In Canada, cryptocurrency is treated as a commodity, and gains are taxed as either capital gains or business income depending on how you trade. Moving coins between your own wallets and accounts is not a disposition, so there is nothing to report for the move itself.
Canada does differ from the US in two important ways:
- Adjusted cost base (ACB) averaging. The CRA uses an average cost for identical property, so all your bitcoin shares one ACB no matter which wallet it sits in. Transfers do not change your ACB, but you still need records to prove it.
- Gifts are dispositions. Unlike in the US, gifting crypto to someone other than your spouse or common-law partner is generally treated as if you sold it at fair market value. You may owe tax on the gain even though you received nothing. Transfers to a spouse can usually roll over at your cost unless you elect otherwise.
Half of a capital gain is included in income under current rules; the proposed increase to the inclusion rate was cancelled in 2025. Our guide to cryptocurrency tax in Canada walks through the CRA rules in full.
How to Track Crypto Transfers Correctly
- Label every transfer. In your exchange or tax software, mark self-transfers as “transfer” or “internal” so they are not counted as sales or as income on the receiving side.
- Keep the transaction ID. Save the on-chain hash, date, amount, sending and receiving addresses. A block explorer such as Etherscan lets you prove both addresses belong to you.
- Carry the cost basis. Note the original purchase date and price for the coins you moved.
- Record fees separately. Write down the fee, the coin used and its value.
- Export statements yearly. Download CSV history from every exchange before you close an account. Exchanges shut down, and records go with them.
- Use crypto tax software or a professional if you have many wallets or chains. Unmatched transfers are the top reason software shows “missing cost basis” errors.
FAQ
Do I pay taxes if I move crypto from Coinbase to my own wallet?
No. Moving coins you own from an exchange to your own wallet is not a sale in the US or Canada. Keep the record so you can match it later.
Is sending crypto to a friend taxable?
In the US, a gift is not a taxable sale for you, though large gifts need Form 709. In Canada, a gift to anyone except your spouse is generally treated as a sale at market value.
Is bridging or wrapping crypto a taxable event?
It depends on the details, and neither the IRS nor the CRA has issued clear guidance for every case. Some treat wrapping (ETH to WETH) as non-taxable and others as a swap. Ask a tax professional if the amounts are large.
Will the exchange report my transfer to the IRS?
Brokers report sales on Form 1099-DA, not simple withdrawals. But if they cannot see your cost basis for coins you deposited, the form may show proceeds with no basis, which you correct on Form 8949.
Sources
- IRS: Frequently asked questions on virtual currency transactions
- IRS: Digital assets
- IRS: About Form 1099-DA
- IRS: Revenue Procedure 2024-28
- IRS: Gift tax FAQs
- CRA: Guide for cryptocurrency users
Educational content only. This is not financial, legal, tax or investment advice. Tax rules change; talk to a qualified tax professional about your situation.