
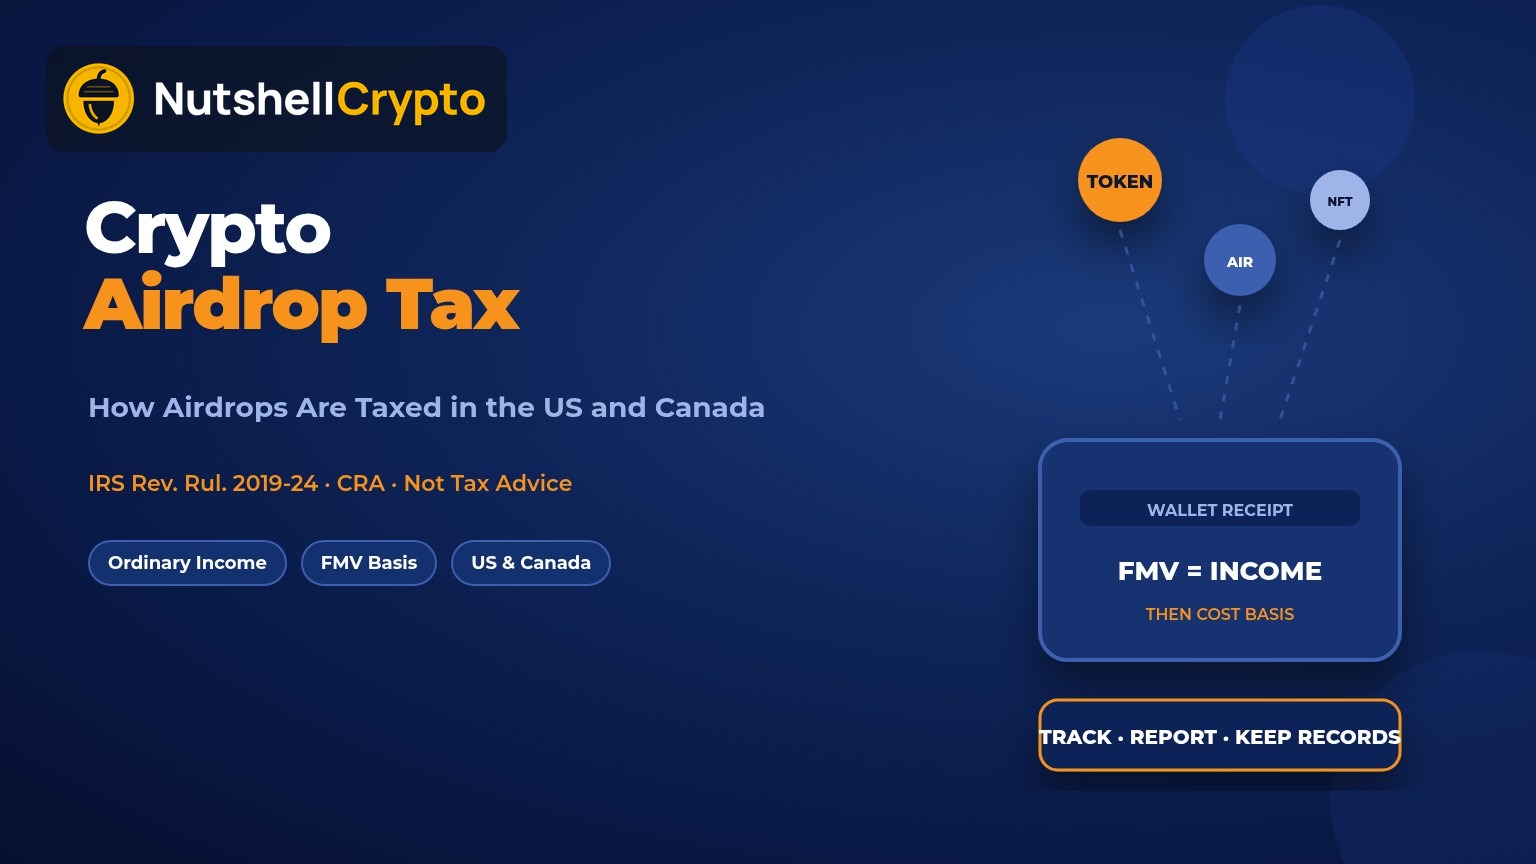
In a nutshell: In the United States, crypto received from an airdrop after a hard fork is generally ordinary income at fair market value when you have dominion and control over the tokens (IRS Revenue Ruling 2019-24). That FMV becomes your cost basis; selling later can create a capital gain or loss. Canada’s CRA has general crypto-asset guidance (income vs capital depends on your circumstances) but no airdrop-specific ruling. Educational only; not tax advice.
Last updated: October 14, 2026.
Crypto airdrop tax questions come up whenever free tokens or NFTs land in a wallet. An airdrop is not always “tax-free money.” In the US, the IRS has published rules for airdrops that follow a hard fork. In Canada, you apply the CRA’s general crypto-asset framework. This guide explains what an airdrop is, how US and Canadian rules work, NFT airdrops, unclaimed tokens, record-keeping, reporting, and a clearly labelled hypothetical example.
For the bigger picture of taxable crypto events, start with our beginner guide to crypto taxes in the US. Simply buying and holding coins is usually not taxed until you dispose of them or receive new coins as income; see if I hold crypto, do I pay taxes?.
Table of contents
- What is a crypto airdrop?
- How crypto airdrops are taxed in the US
- Fair market value, income and cost basis
- Selling airdropped tokens later
- NFT airdrop tax
- Unclaimed, unsupported and worthless airdrops
- Airdrops vs staking rewards
- Record-keeping
- How airdrop income is reported (US)
- Crypto airdrop taxes in Canada
- Worked example (hypothetical)
- FAQ
What Is a Crypto Airdrop?
An airdrop is a way of distributing cryptocurrency units to many addresses on a blockchain. The IRS defines an airdrop that way in Revenue Ruling 2019-24 (checked October 14, 2026): units are sent to the distributed-ledger addresses of multiple taxpayers.
Airdrops show up in a few common shapes:
- Hard-fork airdrops. A protocol change permanently splits a chain. Holders of the old coin may receive units of a new coin. This is the fact pattern Rev. Rul. 2019-24 addresses.
- Promotional or project airdrops. A project sends tokens to wallets that held a related asset, used an app, or completed tasks.
- NFT airdrops. A free NFT is credited to a wallet, sometimes for holders of another collection.
Not every airdrop looks like the hard-fork example in the ruling. The tax analysis still starts with the same questions: Did you receive property? When could you control it? What was it worth in dollars (or Canadian dollars) at that moment?
How Crypto Airdrops Are Taxed in the US
Virtual currency is treated as property for US federal income tax purposes, per IRS FAQs on virtual currency transactions (FAQ A2; these FAQs generally apply to transactions completed before January 1, 2025). Digital assets more broadly—including cryptocurrencies and NFTs—are also treated as property on the IRS Digital assets page (checked October 14, 2026).
Revenue Ruling 2019-24 answers two hard-fork questions:
- If your cryptocurrency goes through a hard fork and you do not receive units of a new cryptocurrency, you do not have gross income from the fork alone.
- If a hard fork is followed by an airdrop and you do receive new cryptocurrency, you have ordinary income under Internal Revenue Code §61 in the year you receive it.
The IRS FAQs restate the same points (Q22–Q25). FAQ A24 says: when you receive cryptocurrency from an airdrop following a hard fork, you have ordinary income equal to the fair market value of the new cryptocurrency when it is received—generally when the transaction is recorded on the distributed ledger—provided you have dominion and control so you can transfer, sell, exchange, or otherwise dispose of it.
Rev. Rul. 2019-24 is written for hard-fork airdrops. Other airdrops (for example, tokens received for completing promotional tasks) are not spelled out in that ruling. General tax principles still matter: receiving property of value can be income under §61, and the IRS digital assets page lists receiving digital assets as a reward or award among the reasons to answer “Yes” on the Form 1040 digital asset question. Facts matter; this is not a substitute for advice from a tax professional.
Fair Market Value, Income and Cost Basis
Two numbers travel together when an airdrop is taxable in the US:
- Income amount. Fair market value (FMV) of the tokens in US dollars when you receive them (when you have dominion and control).
- Cost basis. The same amount you included in income, per FAQ A25 and Rev. Rul. 2019-24. Your basis in the new cryptocurrency equals the amount included in income.
In the ruling’s Situation 2, taxpayer B received 25 units of Crypto S with an FMV of $50 at the time of the airdrop. B included $50 of ordinary income and took a $50 basis in Crypto S.
How do you measure FMV? FAQ A26–A28 explain common methods: the USD amount recorded by an exchange for a facilitated trade; for peer-to-peer or explorer-based values, a blockchain explorer that analyzes worldwide indices; and if there is no published market, the FMV of property or services exchanged. Keep a copy of the price source and timestamp you used.
Selling Airdropped Tokens Later
When you later sell, swap or spend airdropped tokens held as a capital asset, the difference between your proceeds and your cost basis is generally a capital gain or loss. Holding period usually starts the day after you receive the tokens (FAQ A29). Keep this step short here: the full picture of rates, short-term vs long-term, and Form 8949 is in our guide to crypto capital gains tax.
NFT Airdrop Tax
The IRS treats non-fungible tokens (NFTs) as digital assets (Digital assets page, checked October 14, 2026). There is no separate revenue ruling titled “NFT airdrops,” so you apply the same property-income ideas: if you receive an NFT as a reward, award, or other accession to wealth and can control it, its FMV in US dollars when received may be ordinary income, and that amount often becomes your basis. A later sale can create a capital gain or loss.
Some NFTs may raise extra questions (for example, whether a particular NFT is treated like a collectible under other IRS guidance such as Notice 2023-27). Those details are fact-specific. If you store NFTs in a self-custody wallet, our crypto wallet for NFTs guide covers safety basics, not tax forms.
Unclaimed, Unsupported and Worthless Airdrops
Dominion and control is the key timing test in Rev. Rul. 2019-24. Cryptocurrency from an airdrop is generally received when recorded on the ledger, but you do not have receipt at that moment if you cannot exercise dominion and control. The ruling’s example: the airdrop goes to an address in an exchange wallet, and the exchange does not support the new cryptocurrency, so it is not credited to your account. You are treated as receiving it later, when you can transfer, sell, exchange or otherwise dispose of it.
Practical takeaways from that rule:
- Unsupported on an exchange. Income timing may be deferred until the exchange credits the asset or you move it somewhere you can control.
- Unclaimed claim portals. If tokens sit behind a claim process you never complete, whether and when you have dominion and control depends on the facts. The published ruling does not invent a special “ignore forever” exception; it focuses on ability to dispose.
- Worthless or near-zero FMV. If FMV is zero when you first have control, income can be zero and basis can be zero—but you still need a reasonable valuation method and records. A later rise in price does not erase the need to document the receipt-date value.
- Unsolicited dust. Tiny token spam is still property. Document what arrived, when you could control it, and the FMV you used. Do not invent a de minimis IRS rule that the ruling does not state.
Airdrops vs Staking Rewards
Staking rewards are a close cousin: new coins you receive for helping secure a proof-of-stake network. The IRS addressed staking income in Revenue Ruling 2023-14 (dominion and control / FMV in the year received). Keep that topic here to one breath and use our full guide to crypto staking taxes for the worked staking example.
Record-Keeping for Airdrop Taxes
The IRS says you must keep records sufficient to support positions on your return (FAQ A46 and the Digital assets page). For each airdrop, save at least:
- Token or NFT name/ticker and quantity
- Date and time you gained the ability to dispose of it
- Wallet or exchange address that received it
- USD fair market value and the price source (exchange printout, explorer screenshot, CSV)
- Later sale, swap or spend details (date, proceeds, fees)
In Canada, the CRA’s page on keeping books and records of crypto-assets (checked October 14, 2026) asks you to keep adequate books for each transaction and generally retain them for at least six years from the end of the last tax year they relate to. Export exchange histories regularly in case a platform shuts down.
How Airdrop Income Is Reported (US)
Ordinary income from virtual currency is generally reported on Form 1040, Schedule 1 (Additional Income and Adjustments to Income), as the IRS FAQs explain (FAQ A44). Capital gains from later sales go on Form 8949 and Schedule D (FAQ A43).
Answer the Form 1040 digital asset Yes/No question and any Form 1099-DA statements carefully; our short guide to the Form 1040 digital asset question and 1099-DA covers that without repeating the full tax overview here.
Crypto Airdrop Taxes in Canada
The Canada Revenue Agency publishes an Information for crypto-asset users and tax professionals guide (checked October 14, 2026). As of that check, the CRA has not published a standalone “airdrop” ruling like IRS Rev. Rul. 2019-24.
What the CRA does say, in plain terms:
- Crypto-asset dispositions (selling, trading for another crypto-asset, using crypto to buy goods or services, gifting) can create business income or a capital gain or loss, depending on the facts. See the CRA page on reporting income from crypto-asset transactions.
- Whether an activity is business income or capital depends on your circumstances (frequency, intention, time spent, and other factors the CRA lists). Half of a capital gain is generally included as a taxable capital gain when the disposition is on account of capital.
- You must use a reasonable, consistent method to value crypto-assets in Canadian dollars (CRA: valuing crypto-assets).
Because receipt of an airdrop is fact-specific in Canada, many people document the CAD fair market value when tokens arrive, ask a Canadian tax professional whether that receipt is income in their situation, and in any case track adjusted cost base for a later disposition. Country-level walkthroughs live in our cryptocurrency tax in Canada guide.
Worked Example (Hypothetical Numbers)
This example is labelled hypothetical. It is not a real taxpayer, exchange quote or tax filing. It only shows the arithmetic the US guidance describes.
| Step | What happens (hypothetical) | Tax idea |
|---|---|---|
| 1. Receipt | On June 1, 2026, you receive 1,000 TOKEN from a hard-fork airdrop. You can sell them immediately. A reputable price source shows TOKEN at $0.40 each. | Ordinary income of $400 (1,000 × $0.40). Cost basis in the 1,000 TOKEN = $400. |
| 2. Hold | You hold the tokens in your own wallet for several months. Price moves around; you do not sell. | No additional tax from price moves alone while you only hold (same idea as our holding guide). |
| 3. Sale | On December 10, 2026, you sell all 1,000 TOKEN for $0.55 each ($550 total), with $10 of fees, so net proceeds are $540. | Capital gain ≈ $540 − $400 = $140 (short-term if held one year or less). Report on Form 8949 / Schedule D. |
If instead the exchange never credited TOKEN and you never gained the ability to dispose of it in 2026, Rev. Rul. 2019-24’s dominion-and-control example suggests you would not treat receipt as occurring on the ledger date alone. Timing follows control, not headlines.
FAQ
Are crypto airdrops taxable in the US?
Often yes when you receive new cryptocurrency from an airdrop after a hard fork and have dominion and control. Rev. Rul. 2019-24 and IRS FAQs Q23–Q24 treat that receipt as ordinary income at fair market value.
Is airdrop income ordinary income or a capital gain?
The receipt is generally ordinary income. A later sale or exchange of the tokens held as a capital asset is generally a capital gain or loss.
What if I never claimed the airdrop?
Focus on dominion and control. If you never could transfer, sell, exchange or otherwise dispose of the tokens, the ruling’s timing rules may mean you have not yet “received” them for income purposes. Document the facts.
Do NFT airdrops get taxed the same way?
NFTs are digital assets. There is no separate NFT-airdrop revenue ruling; apply property and income principles to FMV at receipt when you control the NFT, then track basis for a later sale.
How are airdrops taxed in Canada?
The CRA has general crypto-asset guidance and no airdrop-specific ruling. Dispositions can be business income or capital gains depending on circumstances. Get Canadian advice for your facts, and keep CAD valuations and records.
Where do I report crypto airdrop tax on a US return?
Ordinary airdrop income is commonly reported on Form 1040 Schedule 1; later capital gains on Form 8949 and Schedule D. Also answer the digital asset question on Form 1040 correctly.
Sources
- IRS: Revenue Ruling 2019-24 (hard forks and airdrops) — checked October 14, 2026
- IRS: Frequently asked questions on virtual currency transactions (Q22–Q25, Q44, Q46) — checked October 14, 2026
- IRS: Digital assets — checked October 14, 2026
- IRS: Revenue Ruling 2023-14 (staking rewards)
- CRA: Information for crypto-asset users and tax professionals — checked October 14, 2026
- CRA: Reporting income from crypto-asset transactions — checked October 14, 2026
- CRA: Keeping books and records of crypto-assets — checked October 14, 2026
- CRA: Determining the value of crypto-assets — checked October 14, 2026
This article is for educational purposes only and is not financial, investment, legal or tax advice. Tax rules depend on your facts and can change. Consult a qualified tax professional in your country before filing.